Gold in your hand isn’t automatically safer than gold held by a third party. The risks of third-party gold storage depend on whether you own specific bars or coins and what the storage agreement says about access, withdrawal, insurance and insolvency. Holding bullion yourself reduces reliance on a provider, but makes you responsible for its physical security.
It’s reasonable to want professional storage without giving up control of an asset you own. Start by understanding the legal ownership structure and the obligations the provider accepts under the contract.
This article compares allocated, segregated and pooled arrangements, then explains how provider, counterparty and contractual risks differ from the practical risks of holding gold yourself. Use these distinctions to assess access to your bullion and the strength of your ownership records.
Key Takeaways
- Read the ownership terms closely: a claim to a quantity of gold is different from ownership of identified bars or coins.
- Look beyond vault security and understand how the agreement handles insurance, withdrawal, sale and insolvency.
- Compare provider storage with keeping bullion yourself, including who bears responsibility for security and access.
- Use statements and audit information to keep your records aligned with the holdings attributed to you.
1. Allocated, segregated, pooled and unallocated ownership
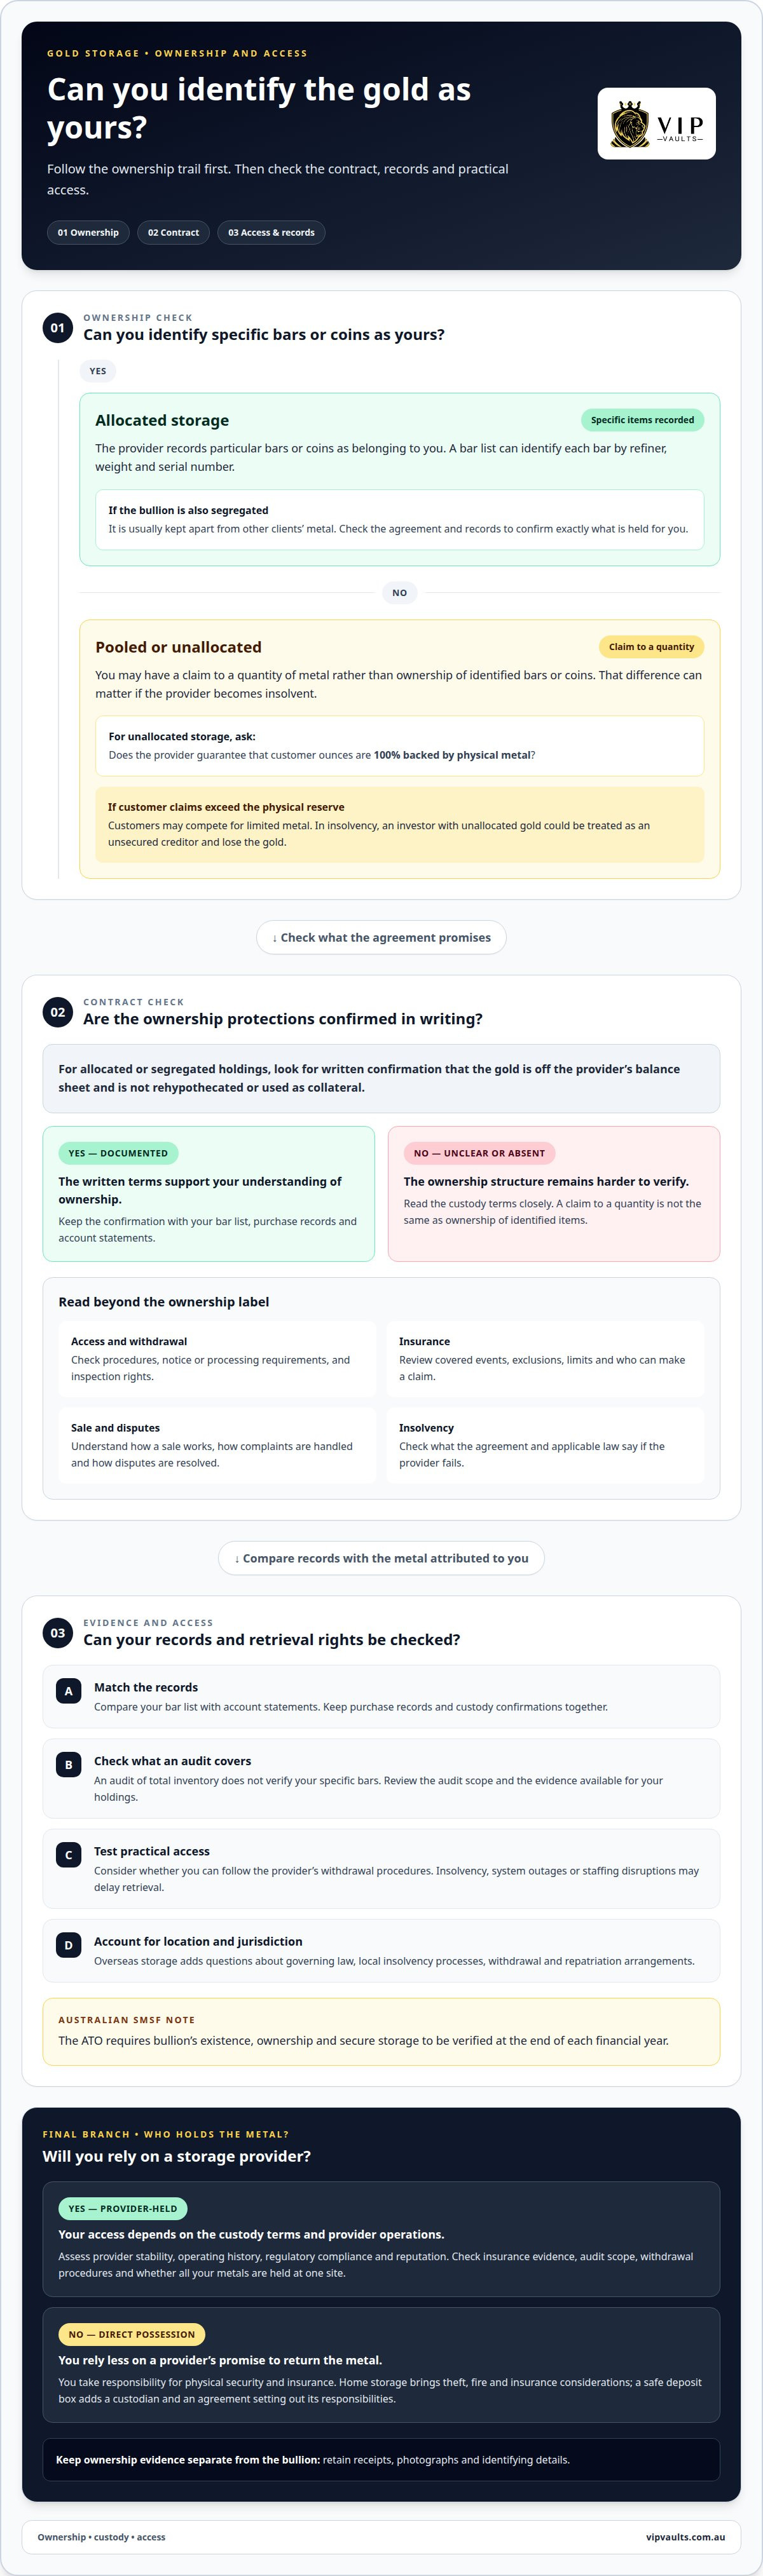
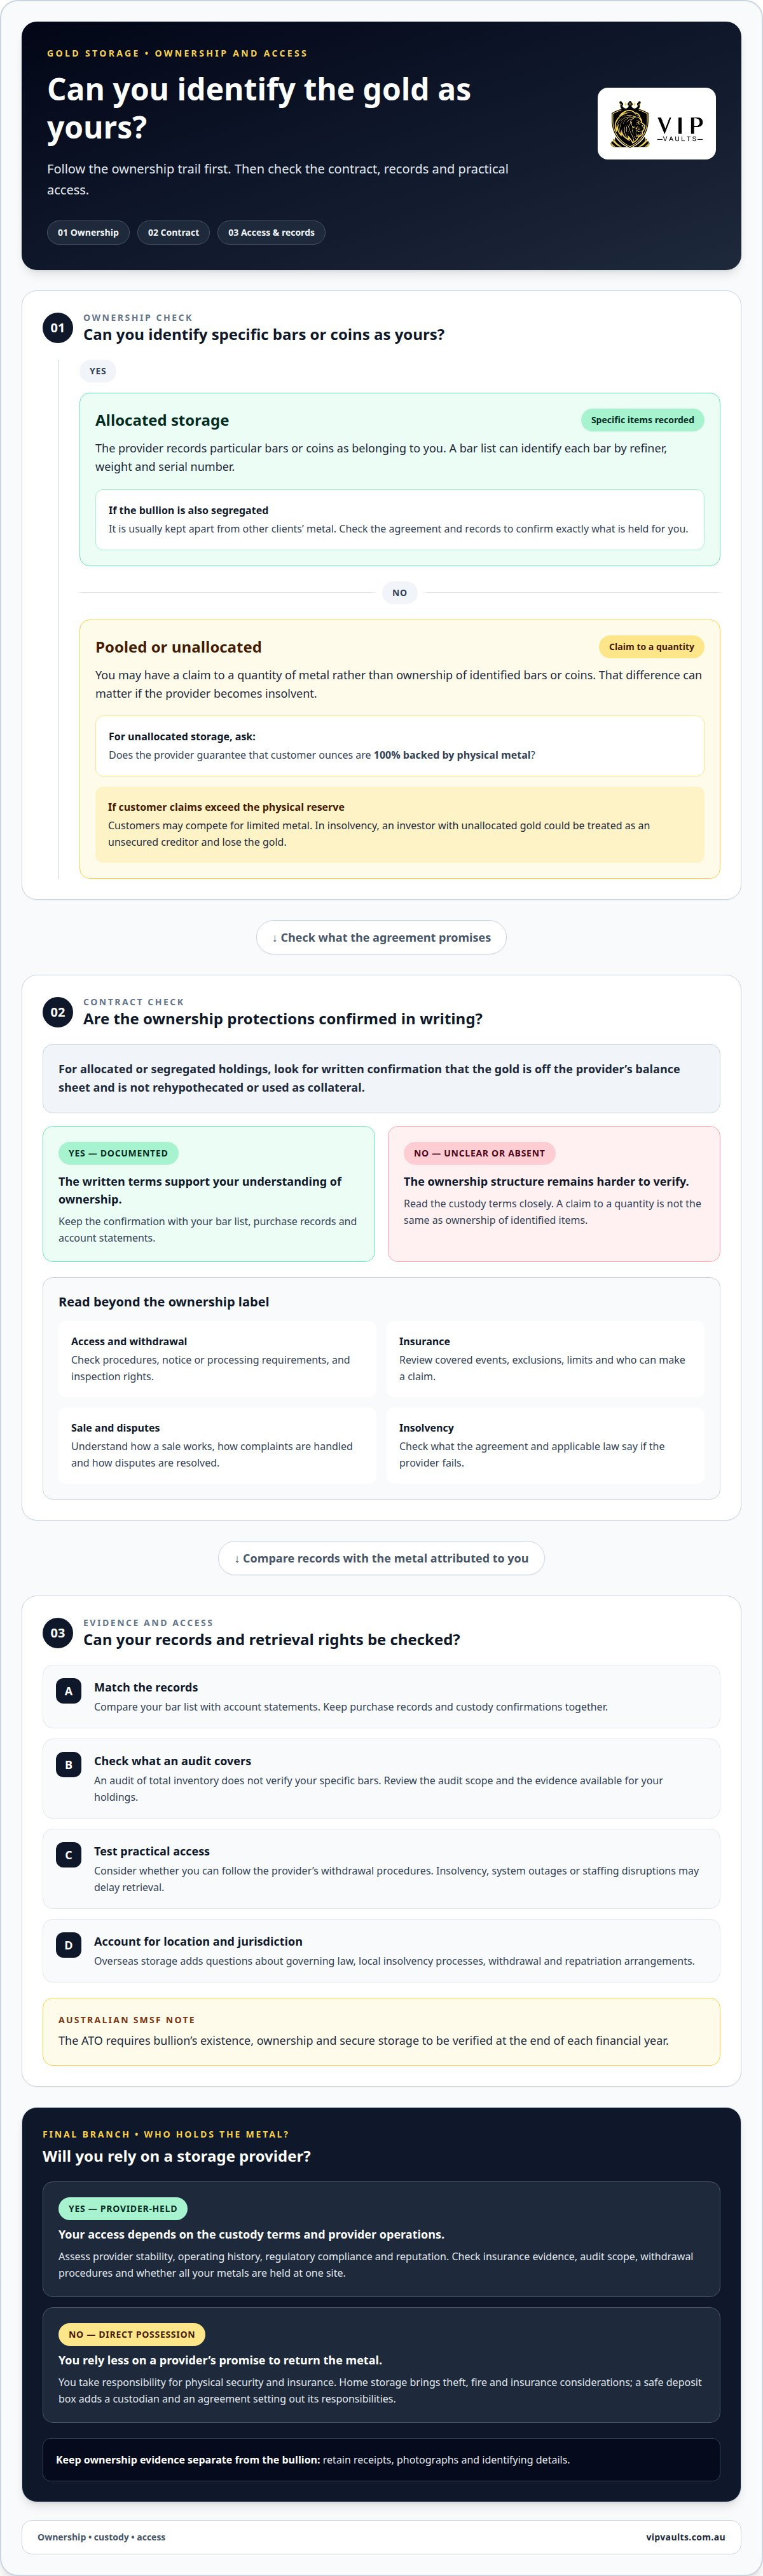
With allocated storage, the provider records specific bars or coins as belonging to you. A bar list can identify each bar by refiner, weight and serial number. Segregated storage usually keeps your bullion apart from other clients’ metal, while pooled or unallocated arrangements may give you a claim to a quantity rather than specific items. That distinction can affect what you can identify as yours if the provider becomes insolvent.
For unallocated storage, establish whether the provider guarantees that customer ounces are 100% backed by physical metal. For allocated or segregated holdings, obtain written confirmation that the gold sits off the provider’s balance sheet and isn’t rehypothecated or used as collateral. Fees can also differ with the ownership structure and custody terms, so compare what each charge covers.
Direct possession of gold and silver removes reliance on a storage provider’s promise to return metal, but leaves physical security and insurance to you. A safe deposit box adds a custodian, and the agreement sets out the provider’s responsibilities. Home storage brings its own theft, fire and insurance considerations. Keep receipts, photographs and identifying details separate from the bullion.
Australia’s 1959 law allowed the government to seize private citizens’ gold when it considered seizure expedient to protect the Commonwealth’s currency or public credit. That historical provision is not, by itself, a statement of current ownership rules. For Australian investors, GST relates to the supply of bullion or storage, while capital gains tax concerns a later disposal and any resulting gain. Transaction and ownership records help distinguish those events.
Overseas storage adds questions about jurisdiction and repatriation. The agreement’s governing law, local insolvency process, withdrawal procedure and arrangements for returning bullion all affect practical access. When assessing a vault, compare your bar list with account statements, review insurance evidence and audit scope, and check inspection and withdrawal rights. An audit of total inventory does not verify your specific bars. For SMSF trustees, the ATO requires bullion’s existence, ownership and secure storage to be verified at the end of each financial year.
2. Advantages and considerations of provider-held gold
Professional storage can reduce the practical burden of storing valuable metals. A facility may provide documented custody, inventory records and insurance coverage against specified losses. This can suit investors who prefer not to keep bullion at home. The trade-off is that access and retrieval depend on the provider’s procedures, staff and operating systems.
Review insurance carefully: check covered events, exclusions, limits and who can make a claim. Theft cover may not address every type of loss. Also establish how withdrawals and sales work, including any notice or processing requirements. A holding is only practically accessible if you can follow the provider’s procedures.
Provider failure can create financial and operational exposure. Insolvency may interrupt access while ownership and custody records are examined; system outages or staffing disruptions can also delay retrieval. Keeping all your metals at one site adds location risk. You can consider separate storage arrangements as part of diversification, while accounting for the extra administration and record-keeping.
In Australia, physical bullion is not covered by the Financial Claims Scheme, according to the Australian Prudential Regulation Authority. That scheme therefore doesn’t protect bullion simply because a provider holds it. The custody agreement and applicable law shape the rights available to customers. Read the terms for ownership, access, withdrawal, complaints and dispute handling before making a decision.
Assess a provider’s financial health, operating history, regulatory compliance and market reputation. Then compare its custody records with the ownership structure described in the agreement. Review insurance evidence, audit scope, inspection rights, withdrawal procedures and the process for selling stored metals. Check whether an audit covers total facility inventory or customer-level holdings. These steps clarify how much your assets depend on the provider and what may happen if normal operations stop.
3. Counterparty risk from third-party storage providers
Counterparty risk is the chance that another party cannot fulfil its obligation. For stored precious metals, that party may be the vault operator, custodian or issuer of a storage record. If you rely on a provider to safeguard and return bullion, its financial stability and operational capacity matter. A secure vault alone cannot resolve a dispute over who owns the metal.
The exposure can be greater with pooled or unallocated holdings. You may have a contractual claim to a quantity of gold or silver rather than rights to identified bars. If customer claims exceed the provider’s physical reserve, customers may compete for limited metal. In insolvency, an investor with unallocated gold could be treated as an unsecured creditor and lose the gold.
Insolvency can also interrupt access to allocated holdings while administrators examine custody records and ownership claims. A bar list, purchase record and account statement can help establish your position, but their value depends on consistent records and clear custody terms. Operational failures, such as lost records or disrupted withdrawal processing, can delay access even without bankruptcy.
Other arrangements carry related risks. A precious-metal certificate depends on the issuer’s ability to deliver metal on request and accurately represent its existence and ownership. A bank safe deposit box keeps the metal separate from the bank’s bullion holdings, but access and responsibilities still depend on the box agreement. Buying a claim to metal is not the same as taking possession of it.
To assess the risk, map each party involved from purchase to withdrawal: seller, custodian, vault operator and any record-keeper. Identify who owes you metal, what evidence records that obligation and what process applies if that party stops operating. Compare the agreement’s insolvency provisions with your ownership documents. This helps distinguish physical custody from a promise to deliver and shows where access depends on another institution.
4. Contractual risks of third-party storage
A contract sets out what the custodian promises, what it excludes and how you can recover your holdings. Read the clauses on ownership, access, withdrawal, liability, insurance, dispute resolution and governing law. For example, a safe deposit box agreement may limit the provider’s responsibility for its contents and restrict access to operating hours. Keeping metal inside a facility does not automatically mean the provider accepts responsibility for every loss.
Insurance for stored precious metals should address theft, loss and other stated risks. The policy wording sets out coverage, exclusions, the claims process and any limits. Standard homeowners or contents policies may apply sub-limits, exclusions or special conditions to bullion, coins, jewellery and other valuables. Check whether the custodian’s policy covers your holdings, who can claim and what evidence is required. A general statement that a facility is insured does not establish what cover applies to your deposit.
Before storing gold, identify the contract’s withdrawal and sale procedures. Find out what notice is required, how identity is verified, whether collection or delivery is available and how a sale instruction is processed. Keep purchase records and account statements together so you can reconcile the quantity released or sold with your portfolio records.
- Mark the notice period and permitted withdrawal method in the agreement.
- Check whether the contract allows partial withdrawals or requires a full holding to be released.
- Review how sale proceeds are calculated, paid and recorded.
- Note any procedure for disputes, lost records or interrupted access.
These terms show where the counterparty’s duties end and your responsibilities begin. For a clear next step in securing valuables, explore Jewellery Storage options and compare the custody arrangement with your needs.
VIP Vaults & Bullion Exchange Perth: Private Vault Rental
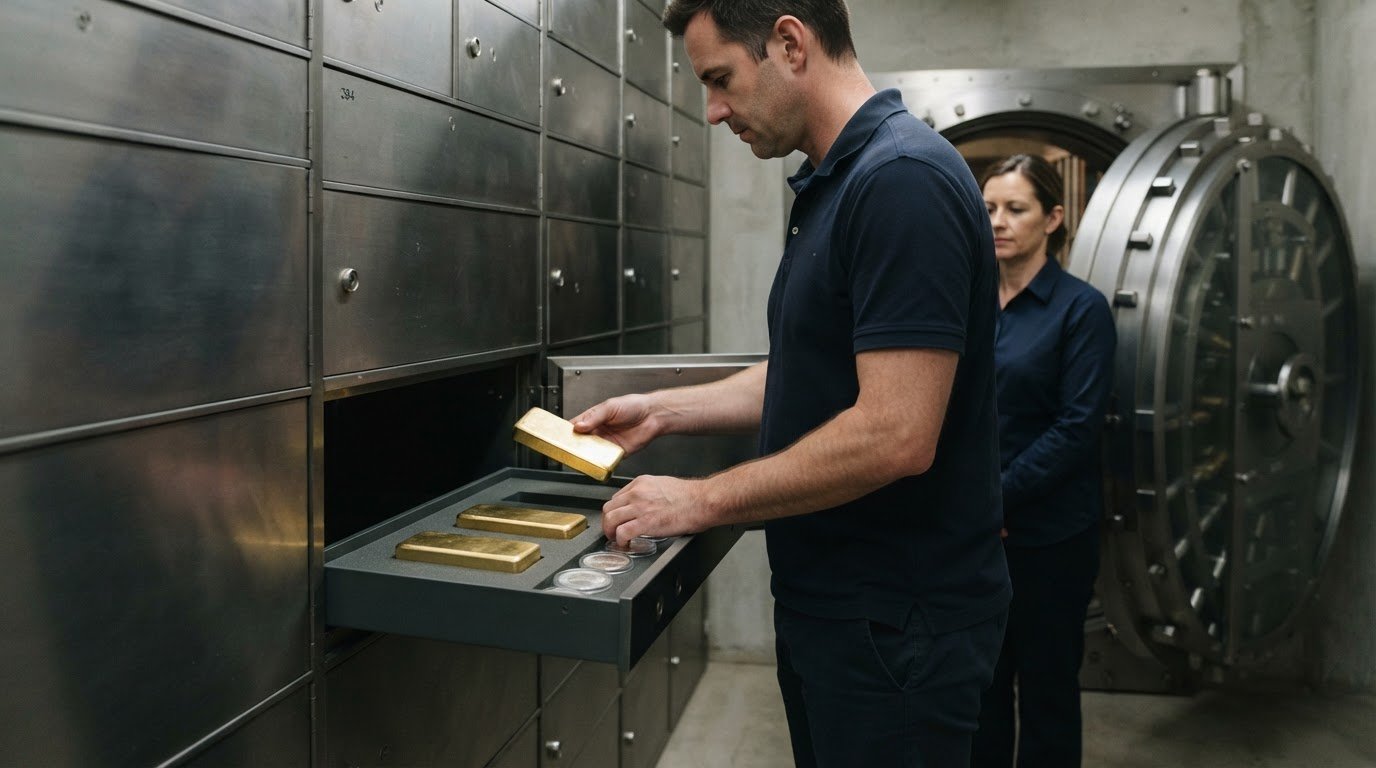
VIP Vaults & Bullion Exchange Perth offers Private Vault Rental and Bullion Locker options for people seeking a dedicated place to store bullion outside their home. If you’re comparing direct physical custody with pooled or unallocated arrangements, consider whether a private vault suits your preference for holding physical assets and reviewing custody terms directly.
You can also explore Gold Bullion and Silver Bullion if you’re considering adding physical metals to your holdings. Before deciding, compare ownership, access, insurance and withdrawal terms with your needs. The right arrangement depends on how you balance personal responsibility with reliance on a storage provider.
Contact VIP Vaults & Bullion Exchange Perth to discuss private storage options, or visit vipvaults.com.au.
Choose a storage arrangement that fits your priorities
Set clear priorities for your bullion: how much direct access matters, how much custody responsibility you want to retain, and which terms you need in writing. The risks of third-party gold storage are easier to assess when you weigh the trade-offs against your circumstances, rather than assuming home storage or a vault is automatically safer.
If you’re considering professional storage, compare the arrangement with your preference for physical ownership and personal control. VIP Vaults & Bullion Exchange Perth offers Private Vault Rental and Bullion Locker options, alongside Gold Bullion. These are practical options to consider when deciding how physical metals fit into your wider wealth plans.
Take the time to choose deliberately, then contact VIP Vaults & Bullion Exchange Perth to discuss your next step. A considered decision can help you move forward with greater clarity and confidence.
Frequently Asked Questions
Gold in Hand or Saving With a Third Party?
Keeping bullion in hand gives you physical possession, but you’re responsible for security and suitable insurance. Third-party storage can reduce the need to keep valuable metal at home, while adding reliance on custody terms and retrieval procedures. If control is your priority, compare ownership of specific items with a contractual claim to metal before choosing how to hold it.
Is it better to save gold with a third party or keep it at home?
Neither option is automatically better. Home storage may suit investors who want direct access and can manage physical security, insurance and records. A third-party facility may suit people who prefer not to keep bullion at home, but access follows its contract and procedures. Compare household security, insurance exclusions, privacy needs and retrieval expectations, then choose an arrangement whose responsibilities you can meet.
What are the main risks of storing gold with a third-party vault?
The main risks of third-party gold storage are delayed access, provider failure, unclear ownership records and insurance gaps. A vault’s physical security does not establish whether your agreement identifies your metal or makes the provider liable for loss. Review who holds the assets, what insurance covers, how withdrawals work and what remedy applies if operations stop. Those terms shape your practical ability to recover your bullion.
Can third-party gold storage providers become insolvent, and what happens to customers' gold?
Yes, a storage provider can become insolvent, and customer outcomes depend on ownership records and the agreement. If specific bullion is allocated and documented, those records can help customers establish their claim; unallocated customers may instead rank as unsecured creditors. Keep purchase evidence, statements and correspondence together, and note the administrator’s process for lodging a claim or seeking the return of metal.
How can investors verify that stored gold is allocated, segregated, and independently audited?
Ask for a client-level bar list with identifying details, then reconcile it against your statements and purchase records. Review an independent auditor’s report to understand its scope and whether it tests specific client allocations or only total vault stock. Check that it covers the relevant custodian and holdings, not just a related entity. Keep dated copies to track changes in your records.
How do Australian allocated gold storage, unallocated accounts, ETFs, and home storage compare?
Allocated storage records particular bars or coins for you, while an unallocated account generally records a quantity of metal rather than identified pieces. An ETF provides investment exposure through a fund, not direct possession of its gold, and involves reliance on the fund’s arrangements. Home storage keeps physical metal with you but makes you responsible for security and insurance. Compare ownership, access and counterparty dependence.