Allocating wealth to bullion is historically the ultimate hedge against market volatility, but inside a self-managed super fund, the metal itself isn't what endangers your capital. The genuine risks of holding physical gold in super stem almost entirely from custodial and regulatory compliance failures.
You likely added physical bullion to your portfolio for absolute security and independence, not to trigger severe ATO administrative penalties or forfeit your fund's concessional tax status. Yet between strict asset separation rules under the SIS Regulations, stringent annual audit demands, and domestic insurance exclusions, managing physical custody correctly can feel deceptively hazardous.
This guide unpacks the statutory framework governing SMSF precious metals and outlines actionable strategies to eliminate compliance, theft, and liquidity risks entirely. We'll examine how independent private vault infrastructure satisfies every legislative hurdle, keeping your retirement wealth thoroughly protected and fully compliant.
Key Takeaways
- Understand why domestic safes trigger severe ATO scrutiny under the sole purpose test and separation of assets rules, creating avoidable non-compliance penalties.
- Identify the core risks of holding physical gold in super, separating legislative custody requirements from broader currency and market volatility.
- Learn how to document a rigorous investment strategy that accounts for bullion liquidity friction, particularly when funding mandatory pension drawdowns.
- Discover why dedicated private vault rentals streamline the annual independent audit process by providing objective, serialised proof of physical custody.
- Master the compliance checklist required to execute arms-length bullion acquisitions correctly without violating related-party transaction prohibitions.
The Primary Regulatory Risks: ATO Compliance and the SIS Act
Holding tangible precious metals within a self-managed fund requires meticulous adherence to superannuation law. Unlike liquid equities or cash accounts, tangible commodities face intense regulatory oversight. Understanding the statutory risks of holding physical gold in super protects trustees from severe operational and financial penalties under the Superannuation Industry (Supervision) Act 1993 (SIS Act).
Under Section 10 of the SIS Act, the Australian Taxation Office (ATO) differentiates between investment-grade commodities and decorative personal assets. Allocating capital to gold as an investment requires bars or cast ingots traded specifically on the basis of purity and weight, rather than rarity or artistic value. Failing to establish this distinction compromises fund operations from day one.
The Sole Purpose Test and Personal Use Traps
Section 62 of the SIS Act mandates that your super fund exists solely to provide retirement benefits to members. Deriving any present-day personal or financial utility immediately breaches this requirement. You cannot display fund-owned gold in a personal residence, showcase it to business associates, or handle it as private property.
A breach of the sole purpose test is a civil contravention that carries significant legal ramifications:
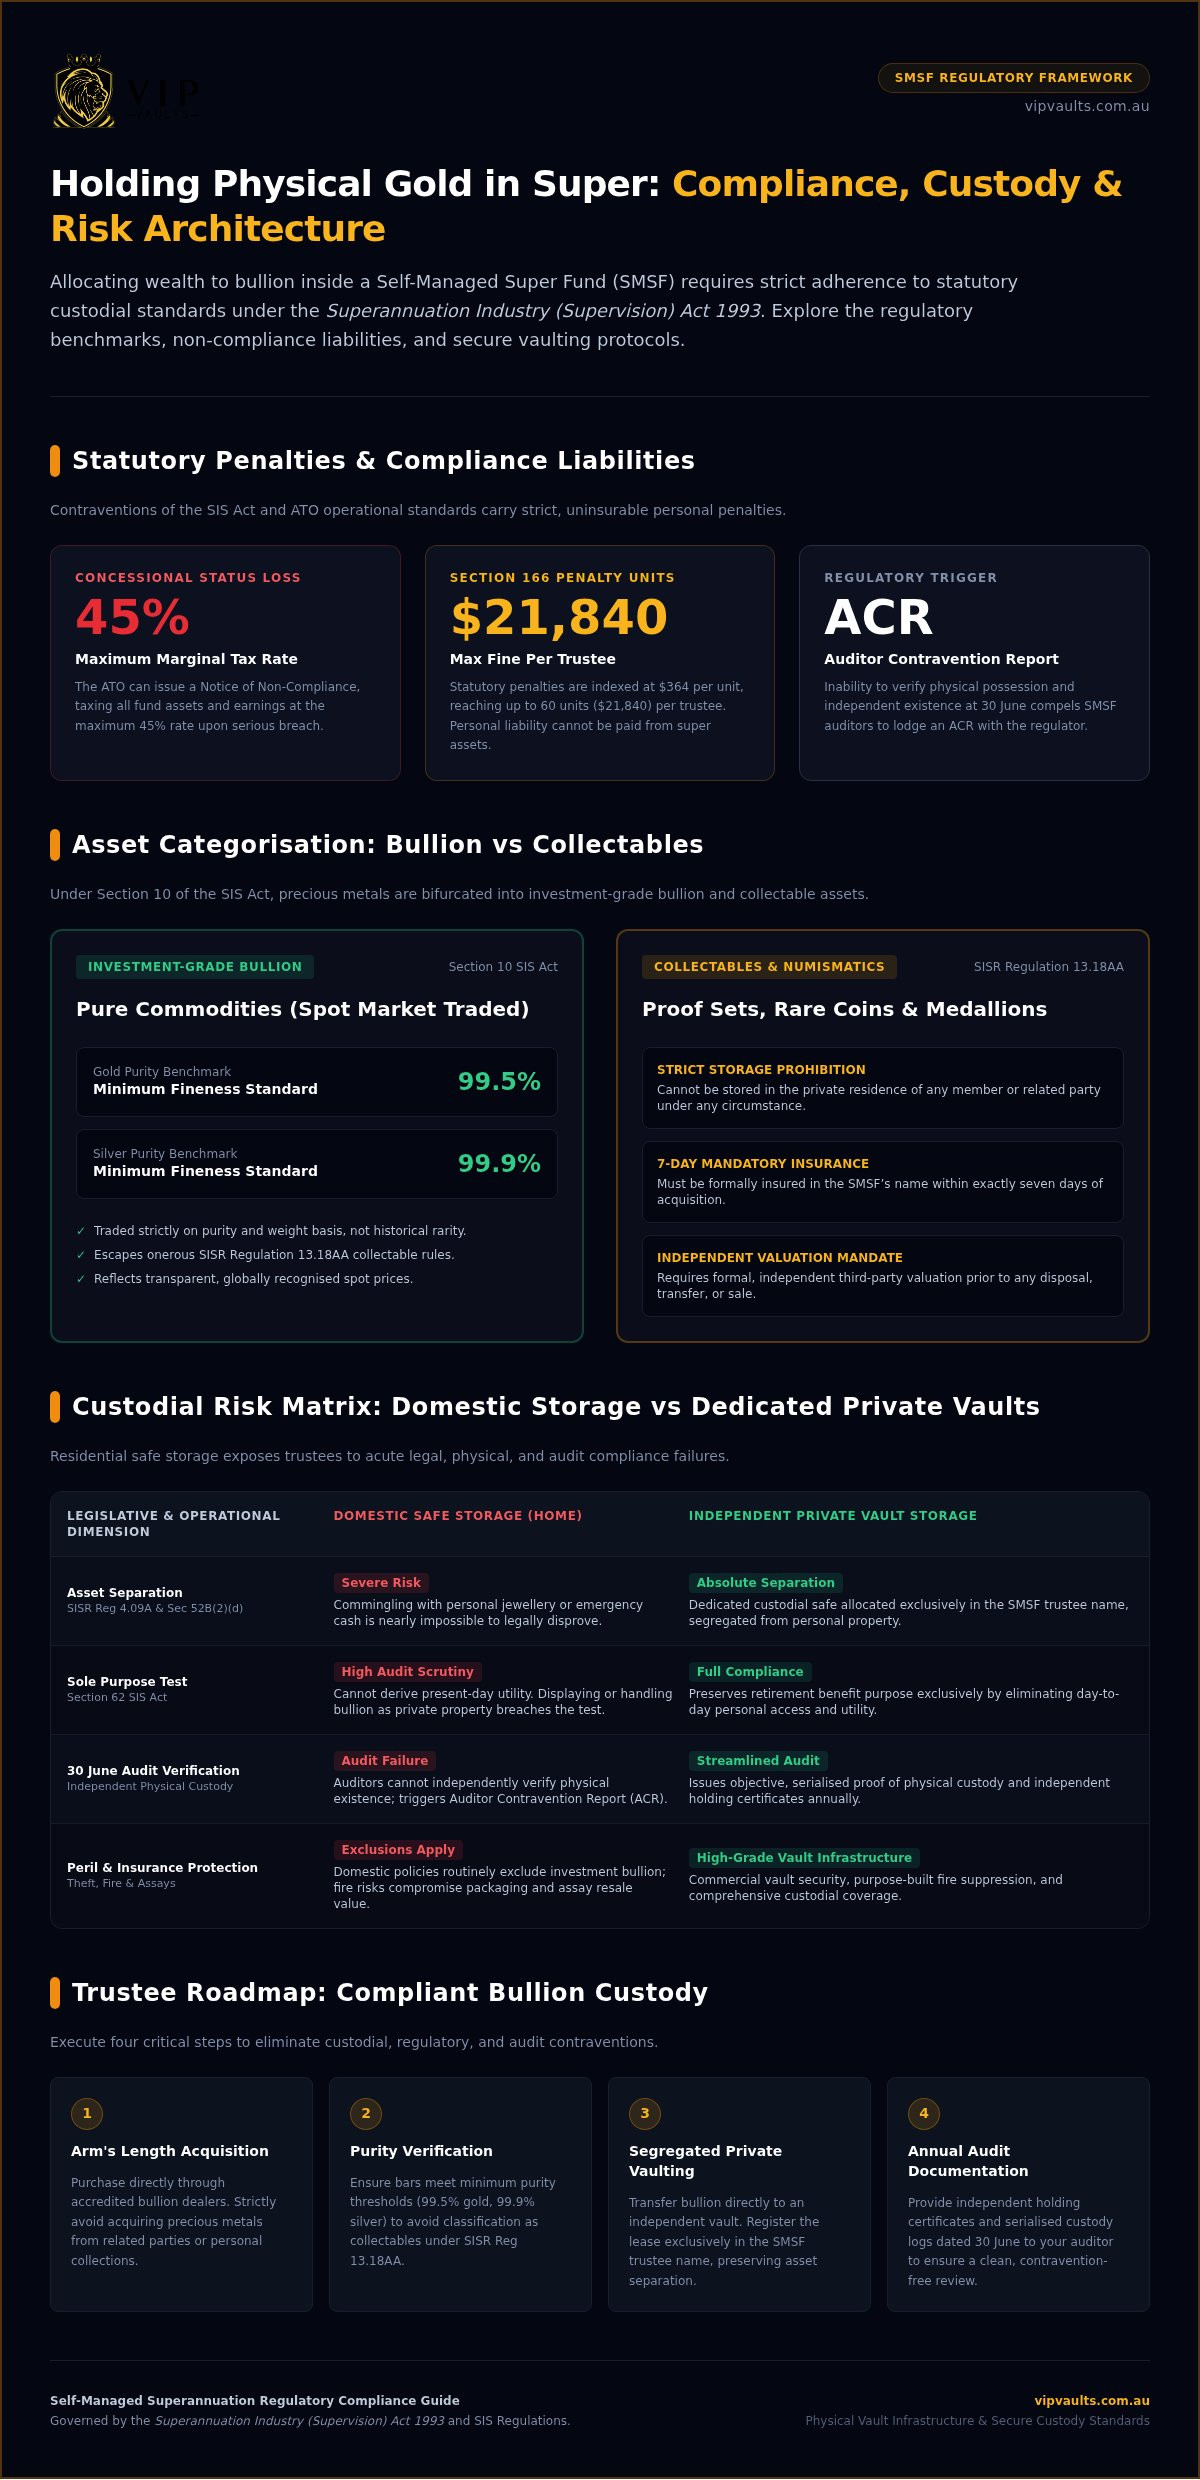
- Loss of concessional tax status: The ATO can issue a Notice of Non-Compliance, taxing fund assets and current earnings at the maximum 45% marginal rate.
- Administrative penalties: Under section 166, trustees face personal liability, with financial penalties indexed at $364 per unit, reaching $21,840 per trustee for severe 60-unit breaches.
- Disqualification: Directors risk formal disqualification from operating any superannuation entity.
Collectables vs Investment-Grade Bullion Standards
Navigating the risks of holding physical gold in super requires recognising the line between pure bullion and collectables. Pure bullion bars meet strict fineness standards, requiring a minimum 99.5% purity for gold and 99.9% for silver. These assets reflect spot market prices.
Conversely, rare numismatic coins, medallions, and historical proof sets fall under Superannuation Industry (Supervision) Regulations (SISR) Regulation 13.18AA. Collectable assets attract complex compliance requirements:
- Strict prohibition against storage in a private residence of any member or related party.
- A mandatory requirement to insure the asset in the fund's name within seven days of acquisition.
- Formal, independent third-party valuations documented before any disposal or transfer.
Acquiring pure, accredited bullion bars avoids the onerous compliance burdens of Regulation 13.18AA. However, maintaining strict custody outside personal reach remains essential for every compliant trustee.
Custodial and Physical Security Risks: Why Home Safes Breach Compliance
Many trustees assume that because pure bullion escapes the collectables rule under SISR 13.18AA, locking bars in a domestic safe is legally acceptable. This assumption represents one of the most perilous custodial traps in self-managed super. The physical and statutory risks of holding physical gold in super multiply exponentially the moment fund assets enter a private residence.
The Legal Hazards of Residential Bullion Storage
Under SISR Regulation 4.09A and Section 52B(2)(d) of the SIS Act, trustees must keep fund assets strictly separate from personal property at all times. Placing fund-owned gold in a home safe alongside personal jewellery, emergency cash, or personal documents makes commingling almost impossible to disprove.
Independent SMSF auditors cannot verify physical existence or custody at 30 June without objective evidence. Without independent holding certificates, the auditor must lodge an Auditor Contravention Report (ACR) with the regulator. Storing retirement bullion at home contravenes core ATO SMSF investment requirements, exposing trustees to direct administrative penalties that cannot be paid or reimbursed using superannuation assets.
Physical Vulnerabilities and Insurance Exclusions
Beyond regulatory penalties, residential holding exposes retirement savings to irrecoverable physical peril. Domestic properties face risks of targeted burglary, forced coercion, and structural fires. Fire damage can melt bullion or incinerate its assay packaging, immediately compromising resale liquidity.
Insurance presents an insurmountable hurdle. Standard residential home and contents policies routinely cap precious metal coverage to nominal sub-limits, usually between $1,000 and $5,000. Securing a legitimate standalone policy in the fund's name for a domestic home safe is virtually unobtainable. Because SIS Regulation 4.09 requires trustees to formulate an investment strategy that accounts for asset risk and insurance, maintaining uninsurable bullion at home constitutes a direct breach of duty.
Eliminating these custodial exposures requires professional SMSF gold storage solutions. Independent custodial infrastructure provides physical segregation, fully underwritten risk coverage, and annual audit certification. Establishing an allocated bullion locker with a specialised partner like VIP Vaults guarantees that your tangible assets remain discreet, fully insured, and completely isolated from personal affairs.
Market, Liquidity, and Valuation Risks of Tangible Gold Holdings
Physical bullion offers unparalleled independence from counterparty insolvency, but tangible commodities introduce financial dynamics distinct from digital equities. Managing the practical risks of holding physical gold in super demands a grounded understanding of liquidity, cash flow mechanics, and market spreads.
Gold pays no dividends, distributions, or interest. In an SMSF environment, holding a large weighting in non-yielding commodities directly influences fund solvency. Official guidance on Moneysmart SMSF trustee responsibilities highlights that trustees remain personally responsible for maintaining fund liquidity, regardless of market movements or asset allocation preferences.
Absence of Yield and Cash Flow Constraints
An SMSF incurs non-negotiable operational liabilities every year. Accounting fees, supervisory levies, independent audit charges, and private vault rental costs require immediate liquid currency. If your fund allocates excessive capital to bullion without maintaining an adequate cash buffer, satisfying these statutory expenses becomes problematic.
This liquidity constraint compounds significantly when members transition into pension phase. Trustees must execute mandatory minimum annual pension drawdowns in cash. You cannot transfer physical fractions of a cast bullion bar to satisfy minimum pension payments. Meeting drawdown obligations requires selling whole bars, which can force liquidations during unfavourable spot market dips.
Liquidity Friction, Premiums, and Authenticity Risks
Liquidating physical bullion involves logistical considerations absent from listed equities. A transaction doesn't execute at the click of a mouse. Selling physical bars introduces secondary market friction that impacts your net investment return:
- Bid-ask spreads: Dealers purchase bullion below the prevailing spot price and sell above it. Frequent reallocations erode capital through these transactional margins.
- Assay and verification delays: Secondary-market bars lacking clear provenance or original tamper-evident assay packaging often require destructive testing or ultrasound authentication before a dealer accepts them, delaying settlement.
- Logistics and transport: Moving heavy physical metals securely to a bullion dealer introduces secure transit costs and operational friction.
Mitigating these secondary risks of holding physical gold in super requires sticking strictly to internationally recognised, LBMA-accredited bars and sovereign minted coins. Cast ingots from accredited refiners retain universal liquidity, tight buyback margins, and immediate verification among established domestic dealers.
A Strategic Compliance Checklist for Trustees Holding Super Bullion
Proactive documentation transforms physical metals from a potential regulatory headache into an unassailable store of wealth. Systematic administration neutralises the compliance risks of holding physical gold in super before your annual audit commences.
Following a structured operational protocol ensures every bar acquisition withstands regulatory examination:
- Formulate a comprehensive investment strategy formally addressing risk, return, liquidity, diversification, and asset insurance.
- Execute transactions exclusively through verified bullion dealers at arms length.
- Issue settlement payments directly from the fund's dedicated cash account, never via personal funds.
- Place purchased metals immediately into an independent private vault rental or allocated bullion locker.
- Obtain verifiable 30 June custodial holding certificates for your annual fund audit.
Formulating Compliant Investment Strategies and Ownership
Under SIS Regulation 4.09, your fund's investment strategy must clearly articulate why precious metals align with member retirement objectives. Document how the allocation hedges against currency debasement while confirming that remaining cash buffers cover mandatory operating expenses.
Legal ownership title requires precision. Bullion purchase invoices must reflect the correct legal entity, such as Corporate Trustee Pty Ltd ATF The Superannuation Fund. Section 66 of the SIS Act prohibits acquiring bullion from related parties. Trustees cannot contribute privately owned gold into the fund as an in-specie transfer. Every acquisition must originate from an independent commercial dealer.
Audit-Ready Documentation and Valuation Protocols
The operational risks of holding physical gold in super culminate at the end of the financial year. Approved SMSF auditors require objective evidence validating that physical bars exist and remain in fund ownership as of 30 June.
Independent repository statements solve this reporting requirement completely. A compliant custodial holding statement specifies:
- Individual bar weights, metal fineness, and unique refiner serial numbers.
- Exact end-of-year market valuations derived from published 30 June spot rates.
- Confirmation of allocated physical custody within a segregated facility.
Retain all original tax invoices, assay certificates, and custodial holding receipts in your permanent fund records. To secure fully documented, audit-ready storage for your precious metals portfolio, explore private vault rental options with VIP Vaults.
Mitigating Super Bullion Risks Through Secure Private Vaults
Self-managed super funds require custodial solutions that marry absolute physical protection with stringent legislative compliance. Opting for dedicated non-bank custodial facilities neutralises the operational, custodial, and audit risks of holding physical gold in super, providing a seamless bridge between tangible wealth and statutory oversight.
By moving beyond domestic environments and standard financial institutions, trustees secure an uncompromised barrier around retirement capital. Utilising specialized private vault rental solutions ensures fund assets remain independent, segregated, and completely safeguarded against systemic vulnerabilities.
Allocated Segregation vs Unallocated Counterparty Exposure
Many institutional providers promote "unallocated" gold accounts, presenting them as convenient, cost-effective options. In reality, unallocated bullion transforms physical wealth into an unsecured liability on an intermediary's balance sheet. If the issuing provider experiences insolvency, your super fund stands as an unsecured creditor with no legal claim to specific physical bars.
True asset protection demands allocated segregation. Securing a dedicated bullion locker guarantees that specific serialized bars belong exclusively to your super fund. The facility acts purely as an independent bailee, meaning the contents remain entirely off its corporate balance sheet and completely outside traditional banking systems.
Streamlined Reporting and Institutional Protection Standards
Managing the regulatory risks of holding physical gold in super becomes straightforward when supported by purpose-built custodial infrastructure. Non-bank facilities resolve annual compliance friction through precision reporting and verifiable security:
- Independent certification: Depository holding statements provide approved SMSF auditors with an indisputable Certificate of Existence, confirming quantities, purities, and bar serial numbers as of 30 June.
- Multi-layered defence: Facilities combine biometric protocols, dual-key authentication, seismic monitoring, and constant digital surveillance, deterring coercion and physical theft.
- Comprehensive underwriting: Allocated lockers benefit from specialist, multi-risk insurance underwriters, fulfilling SIS Regulation 4.09 standards without domestic policy sub-limits.
Establishing an allocated locker provides complete custodial clarity. You retain full control over your physical bars while effortlessly fulfilling every evidentiary requirement demanded by the ATO and independent fund auditors.
Safeguard Your Retirement Wealth with Complete Custodial Confidence
Holding physical precious metals within a self-managed super fund offers an enduring hedge against systemic volatility, but long-term success demands uncompromised adherence to the law. Effectively eliminating the primary risks of holding physical gold in super requires moving past domestic storage traps, upholding strict arm's-length acquisition standards, and preserving absolute separation between personal property and superannuation assets.
Purpose-built non-bank custodial infrastructure solves these statutory demands effortlessly. With allocated bullion locker access, physical asset segregation, and comprehensive independent holding statements, your fund satisfies annual 30 June audit requirements with total precision. VIP Vaults pairs sourcing of investment-grade, LBMA-accredited bullion with private vault rental solutions designed specifically to protect self-managed portfolios.
Don't let custodial oversights or inadequate safe-keeping jeopardise your hard-earned retirement savings. Take decisive action to protect your fund's complying status and establish lasting peace of mind. Secure your retirement bullion in compliant private vault storage with an independent specialist dedicated to safeguarding your wealth.
Frequently Asked Questions
Can I legally store physical gold held in my SMSF in a home safe?
While pure bullion technically avoids the collectables storage ban under SISR 13.18AA, storing fund gold at home breaches core superannuation laws. It violates asset separation rules under SISR 4.09A by commingling retirement assets with private property. Domestic safe-keeping also triggers sole purpose test breaches and prevents approved auditors from independently verifying asset custody, prompting mandatory Auditor Contravention Reports.
What happens if my self-managed super fund breaches the Sole Purpose Test with gold?
Breaching Section 62 of the SIS Act carries catastrophic regulatory consequences. The ATO can declare your fund non-complying, subjecting fund assets and earnings to a punitive 45% flat tax rate. Individual trustees face personal administrative fines of $21,840 per trustee for severe contraventions under current indexation rates. These statutory penalties must be paid personally and cannot be reimbursed by fund assets.
Does the Australian Taxation Office allow physical inspection of my fund's bullion?
The ATO mandates that approved SMSF auditors obtain sufficient, objective evidence verifying asset existence and ownership at 30 June. While regulators rarely perform direct residential checks, auditors must verify custody independently. Storing bullion in an independent private vault produces verified holding certificates and Certificates of Existence, satisfying audit standards seamlessly without requiring invasive, costly home inspections.
What is the difference between allocated and unallocated gold for an SMSF?
Allocated gold provides your super fund with direct, legal title to specific, serialised physical bars secured in a segregated bullion locker. The vault acts purely as a custodial bailee. Unallocated gold is simply an unsecured debt obligation on a dealer's balance sheet. Relying on paper balances increases counterparty insolvency exposure, amplifying the risks of holding physical gold in super.
How is physical gold valued for annual SMSF accounting and audit purposes?
The ATO requires all fund assets to reflect true market value on 30 June each year. Bullion valuations must mirror published global spot rates multiplied by total troy ounces, without adding subjective markups. Independent private vault holding statements detail verifiable bar serials, precise purities, and documented 30 June market values, providing auditors with fully compliant, objective evidence.
Are bullion coins treated differently to cast bars under superannuation legislation?
Standard sovereign bullion coins whose pricing reflects physical metal weight, such as legal tender Australian bullion coins, share the same regulatory classification as cast ingots. However, proof sets, historical numismatics, and collector coins carrying substantial premiums above spot metal value fall under SISR 13.18AA collectables rules. These items require separate insurance within seven days and formal independent valuations upon transfer.
Can an SMSF acquire physical gold bullion directly from a fund member?
No. Section 66 of the SIS Act strictly prohibits funds from acquiring assets from related parties or members. You cannot transfer personal gold into your fund as an in-specie contribution, nor can your fund purchase bullion from your private collection. Every bar must be bought at arms length from established dealers using superannuation cash to avoid severe regulatory risks of holding physical gold in super.