What if the digitised numbers on your superannuation statement aren't enough to protect your lifestyle when the next global financial tremor hits? It's a confronting thought, yet many Australians are currently watching market volatility erode their hard-earned savings while interest rates on cash deposits fail to keep pace with the rising cost of living. You've likely found yourself asking, is gold a good investment for retirement Australia, particularly as traditional financial systems face unprecedented pressure. We understand the need for a stable foundation that preserves your purchasing power regardless of what happens on the trading floor.
This 2026 strategy guide explores how physical bullion serves as a robust insurance policy for your future, shielding your wealth from inflation and systemic risks that banks cannot mitigate. We'll provide a clear roadmap for integrating precious metals into your portfolio, covering everything from LBMA-accredited bars to the specific ATO regulations governing SMSF storage. By the end of this article, you'll understand how to secure your retirement through tangible asset ownership and the professional vaulting solutions that keep your wealth private and protected.
Key Takeaways
- Understand why physical bullion acts as a reliable store of value that preserves your purchasing power against domestic inflation.
- Evaluate the evidence behind why is gold a good investment for retirement Australia, specifically focusing on its lack of counterparty risk compared to bank-held assets.
- Learn the critical distinctions between physical ownership and gold ETFs to ensure your strategy avoids the hidden risks of paper-based exposure.
- Navigate complex ATO compliance requirements for SMSF gold storage and discover why professional vaulting is essential to avoid regulatory pitfalls.
- Discover the benefits of utilising independent, high-security facilities that offer LBMA-accredited products for ultimate portfolio stability.
The Role of Gold in an Australian Retirement Portfolio
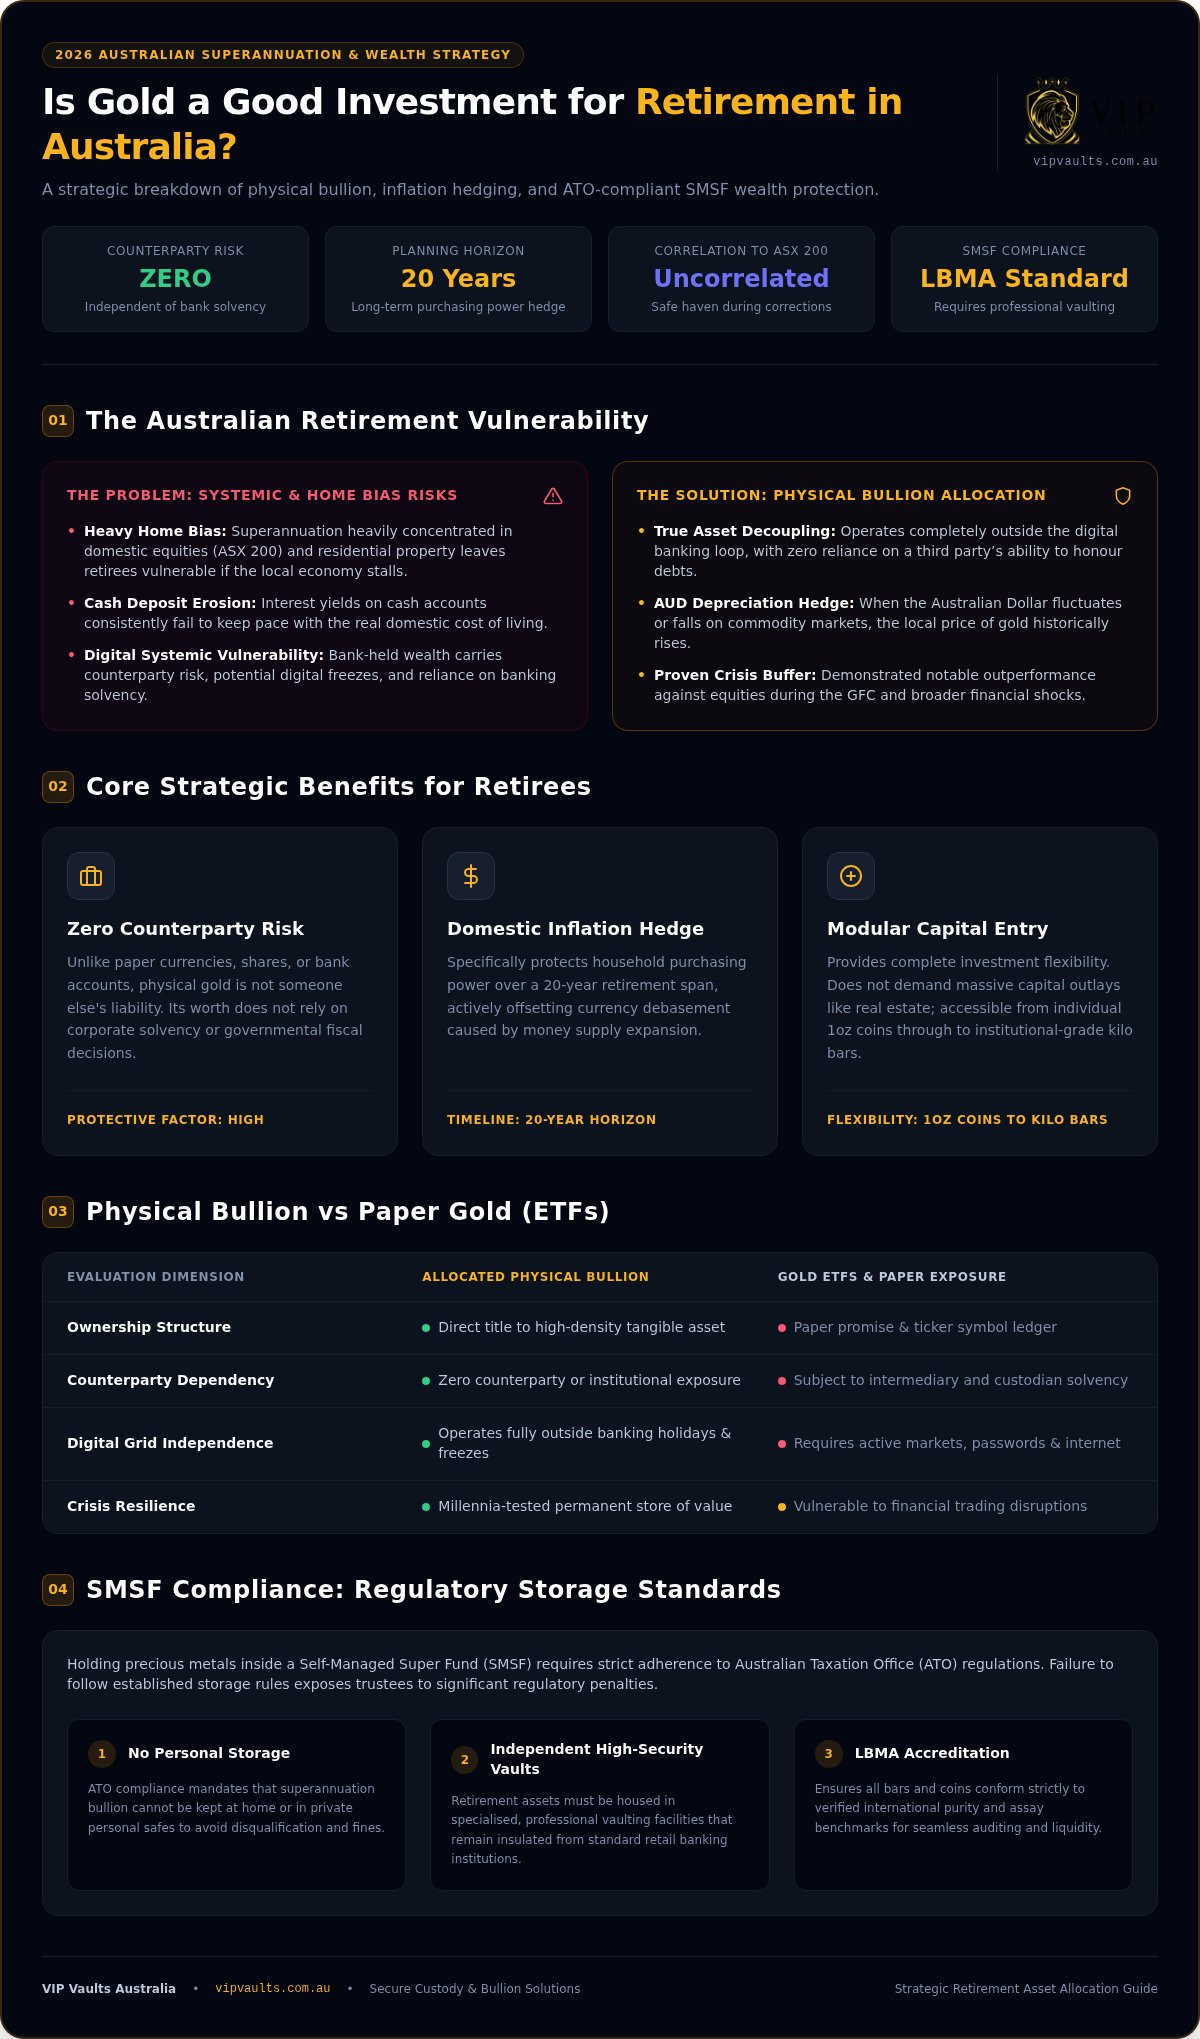
Gold is often misunderstood as a high-risk gamble, yet for those planning their future, its true utility lies in its role as a permanent store of value. Unlike paper currencies or digital entries in a bank ledger, physical gold has no counterparty risk. This means its worth doesn't depend on a bank's ability to pay or a government's fiscal policy. When considering gold as an investment, many Australians look to its history of maintaining wealth over decades. It's an insurance policy for your superannuation. If the share market experiences a sharp correction, physical bullion often moves in the opposite direction, providing a vital buffer for your nest egg.
Historically, gold has demonstrated remarkable resilience during Australian market downturns. During the global financial crisis and more recent economic shocks, gold prices in Australian dollars often outperformed traditional equities. It isn't a speculative trade designed for quick profits. Instead, it's a foundation for a stable portfolio that remains unshakeable when traditional financial systems falter. For many, the answer to whether is gold a good investment for retirement Australia depends on their desire for an asset that exists outside the digital banking loop.
Protecting Your Purchasing Power in 2026
The Australian Dollar (AUD) frequently fluctuates based on global commodity prices and domestic economic shifts. When the AUD weakens, the price of gold in local terms typically rises, effectively protecting your domestic buying power. In an era where traditional savings accounts offer yields that often fail to outpace the cost of living, tangible assets provide a sense of security that digital numbers cannot match. An inflation hedge is a strategic asset allocation designed to preserve the real value of your wealth over a 20 year retirement horizon despite the rising costs of goods and services.
Diversification Beyond the ASX 200
Most Australian retirees suffer from "home bias," where their wealth is heavily concentrated in local shares and residential property. This leaves them vulnerable if the domestic economy stalls. Gold provides an asset class that isn't correlated to the ASX 200 or the local housing market. When geopolitical tensions rise or global markets face instability, demand for physical bullion spikes as investors seek a safe haven. It acts as a silent partner in your portfolio, holding its value while more volatile assets swing wildly. This stability is why many people ask, is gold a good investment for retirement Australia, as they seek to decouple their future from the specific risks of a single market or currency.
Key Benefits of Holding Physical Bullion for Retirees
While most retirement strategies rely on digital ledgers and paper promises, the appeal of physical bullion lies in its absolute tangibility. You aren't just owning a ticker symbol; you're holding a high-density, physical asset that has been recognised as wealth for millennia. This independence from the digital banking grid is a primary reason why retirees frequently ask, is gold a good investment for retirement Australia. Physical gold removes the reliance on a third party's ability to honour their debts. If a financial institution faces a liquidity crisis, your physical bars remain unaffected, sitting securely outside the traditional banking loop.
Gold also offers a "fair go" for every type of investor. Whether you're looking to convert a small portion of your savings into 1oz coins or seeking to move significant capital into kilo bars, the market is accessible. It's a versatile tool for wealth protection that doesn't require the massive capital outlays often associated with investment property. For those seeking to preserve what they've built, exploring secure bullion options provides a pathway to stability that paper assets often struggle to match during times of high inflation.
Tangible Wealth vs. Digital Promises
The risk of digital asset freezing or "banking holidays" is a concern that many Australian retirees take seriously. In a systemic crisis, access to digital funds can be restricted instantly. Physical bars provide a level of security that a balance on a screen simply cannot. History is littered with examples of paper currencies failing or being devalued through excessive printing, yet gold has consistently maintained its purchasing power. It doesn't require a password or an internet connection to exist. It's a permanent, robust form of wealth that you can physically control, offering peace of mind that digital entries can't provide.
High Liquidity in the Australian Market
One of the most practical benefits for retirees is gold's high liquidity. Unlike investment real estate, which can take months to sell and involves significant transaction costs, investment-grade bullion can be liquidated quickly. In Australia, reputable dealers provide transparent buy-back prices, allowing you to access cash when you need it. This ease of movement is enhanced by LBMA accreditation, which ensures your gold is globally recognised and meets the highest standards of purity.
When comparing physical assets to exchange traded funds (ETFs), it's vital to remember that ETFs are financial products subject to market hours and fund management risks. Physical gold is an asset of last resort. It's often more liquid than other tangible investments because the market for gold is global and continuous. This makes it an ideal component for those wondering, is gold a good investment for retirement Australia, as it provides both the security of a hard asset and the flexibility of cash.
Physical Gold vs. Gold ETFs: Which Suits Your Retirement?
When investors first investigate whether is gold a good investment for retirement Australia, they often encounter two distinct paths: physical bullion or Exchange Traded Funds (ETFs). While ETFs offer a convenient way to track the price of gold through a stockbroker account, they represent a fundamentally different strategy than physical ownership. An ETF is a paper contract, a digital promise that provides exposure to price movements without giving the investor direct control over the underlying metal. For a retiree seeking absolute security, the distinction between owning a financial product and owning a tangible asset is vital.
The "if you can't hold it, you don't own it" philosophy is a cornerstone of wealth protection. Physical bullion provides several advantages that paper markets cannot replicate:
- Direct Title: Your name is on the physical asset, not just a ledger entry in a managed fund.
- Zero Counterparty Risk: Physical gold doesn't rely on a fund manager's solvency or a bank's ability to settle trades.
- Systemic Independence: Bullion exists outside the digital banking grid, remaining accessible even during financial market closures.
- Physical Redemption: Most gold ETFs do not allow retail investors to take physical delivery of the metal, leaving them with only cash settlement options.
The Reality of Gold ETF Structures
Most gold ETFs are structured as complex financial instruments that track the spot price through derivatives or unallocated gold accounts. This means your retirement capital is vulnerable to fund management decisions and the operational risks of the issuing institution. When setting up an SMSF, as detailed in the ASIC Moneysmart guide to self-managed super funds, trustees must consider the liquidity and security of their chosen assets. Paper markets are also susceptible to high-frequency trading volatility, which can cause price dislocations that don't always reflect the true value of physical gold during a crisis. While ETFs have management fees that erode your capital over time, physical storage costs are often more transparent and provide a higher level of security.
Why Physical Bullion Wins for Long-Term Security
For those prioritising a twenty year retirement horizon, the stability of physical gold is unmatched. It represents wealth that has no expiry date and requires no digital infrastructure to maintain its value. There is a profound psychological and practical difference between the unshakeable peace of mind provided by a high-security private vault and the digital vulnerability of a stockbroker account. By holding physical bars, you remove the middleman from your wealth protection strategy. This independence is often the deciding factor for those concluding that is gold a good investment for retirement Australia, as it ensures their nest egg remains a tangible reality regardless of market volatility.
SMSF Compliance: Storing Retirement Gold Securely
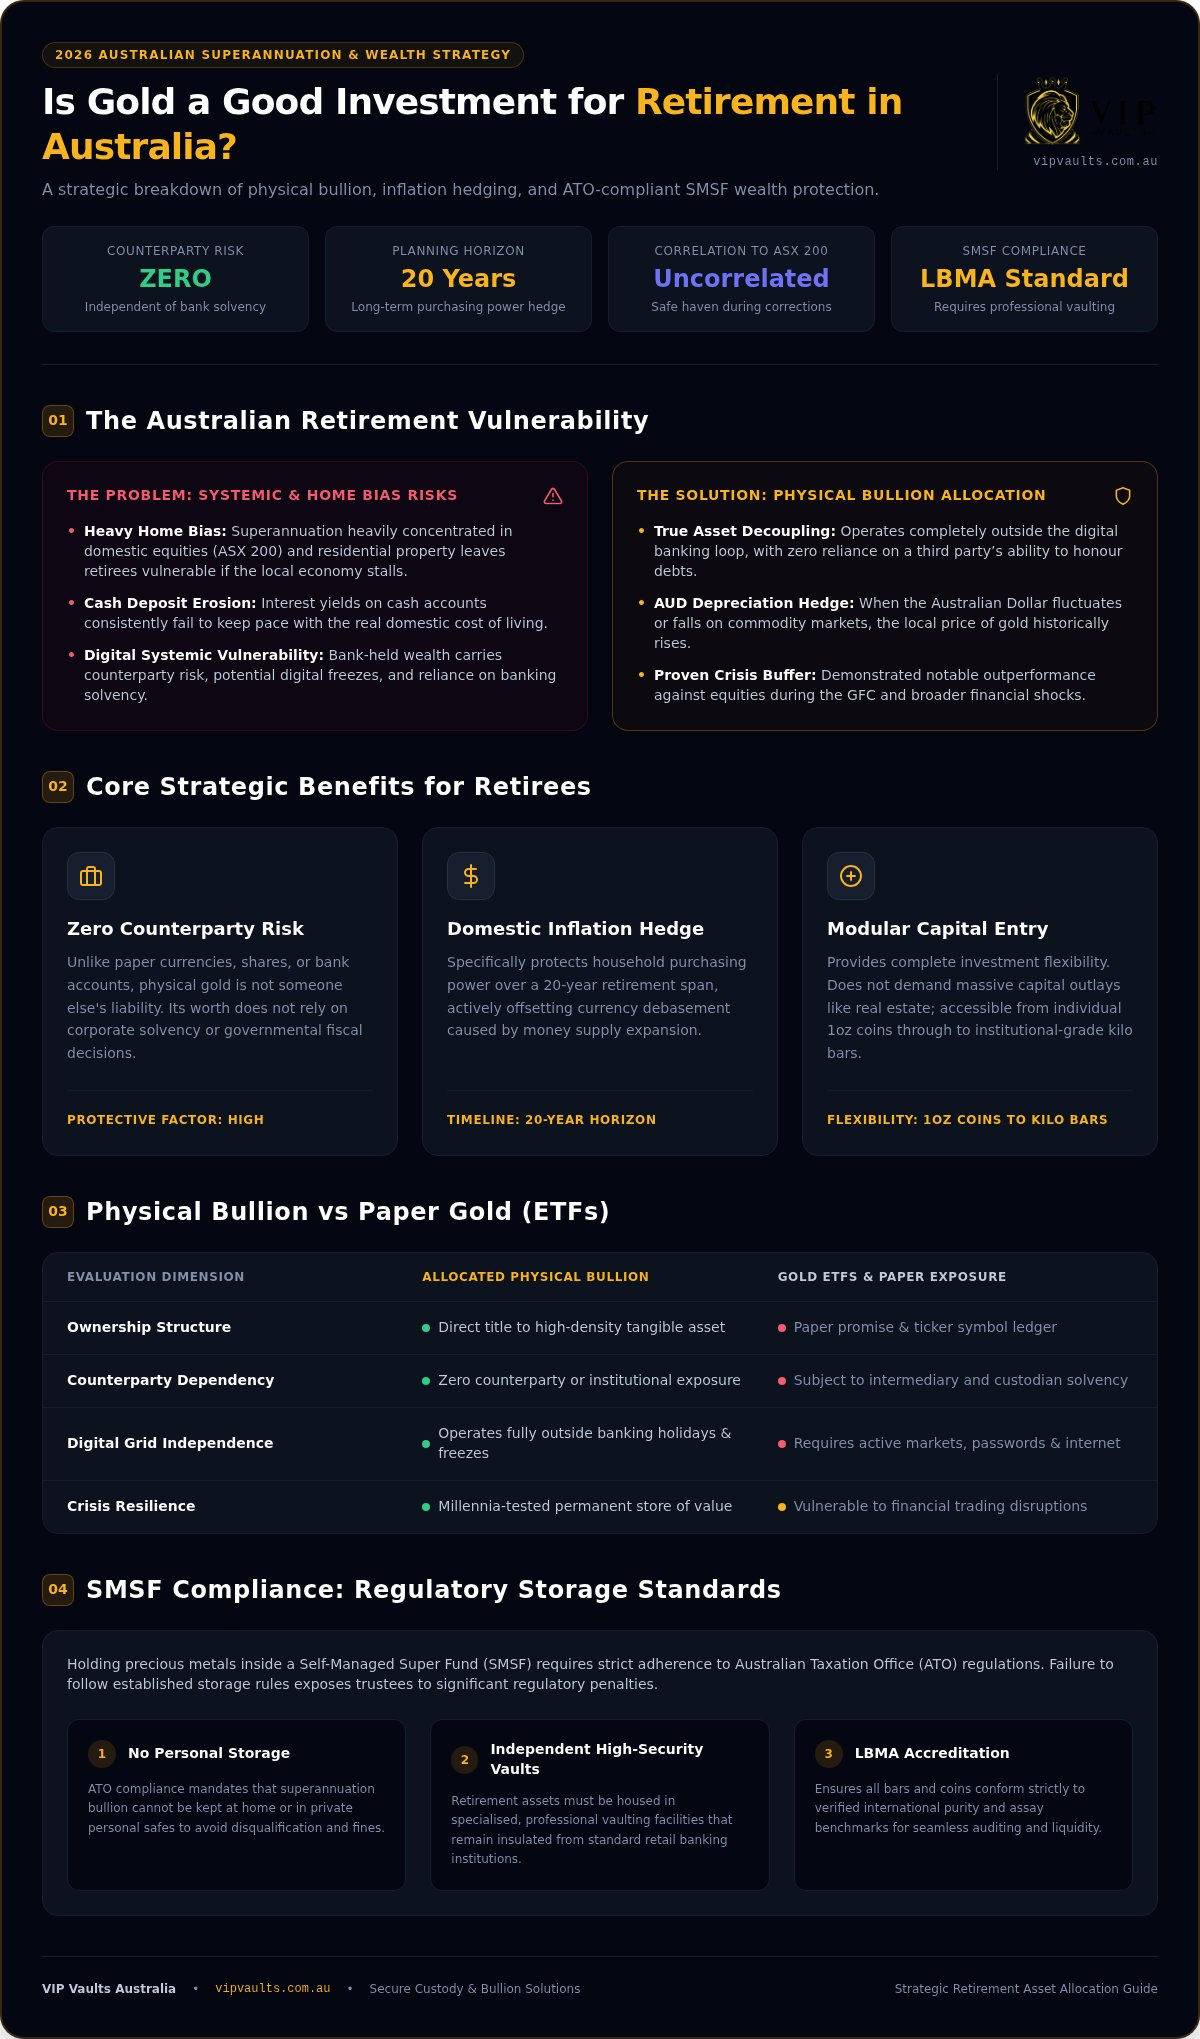
Establishing whether is gold a good investment for retirement Australia is only the first step. For trustees, the real challenge lies in the logistical demands of the Australian Taxation Office (ATO). Managing physical bullion within a Self-Managed Super Fund (SMSF) requires strict adherence to the 'sole purpose test'. This regulation mandates that all fund assets must be held exclusively to provide retirement benefits. Any personal use, or even the appearance of commingling bullion with private assets, is strictly prohibited. Many trustees inadvertently fall into the 'Home Storage Trap' by assuming a high-quality home safe is sufficient. In reality, the ATO heavily scrutinises home storage because it's nearly impossible to provide the independent verification required to prove the assets are held solely for the fund.
Professional vaulting removes this regulatory headache. By using a specialised facility, you ensure your bullion is held in an environment that meets the highest security protocols. This independence from your personal residence is a key indicator to auditors that the fund is operating correctly. If you're looking to protect your wealth while staying compliant, securing a private bullion locker provides the necessary distance between your retirement savings and your daily life.
ATO Audit Requirements for 2026
Compliance in 2026 demands a comprehensive paper trail. Your fund's auditor will require an annual audit certificate and a formal storage agreement that confirms the bullion's existence and security. These documents must verify the purity and weight of the bars; using LBMA-accredited products often simplifies this valuation process. Failing to meet these standards can result in severe penalties. The fund could be declared non-complying, which potentially triggers a tax rate of 45% on the fund's total assets.
The Advantages of Private Vault Storage
Utilising a private vault provides the independent verification and comprehensive insurance that auditors require. Unlike traditional banking institutions, which may have limited options for physical asset storage, an independent facility offers a dedicated sanctuary for your wealth. This setup ensures your gold is physically robust and fully protected against theft or damage. For a detailed breakdown of these requirements, see our guide on SMSF Gold Storage: Investing in Gold in Australia (2026). This approach guarantees that your investment remains outside the financial system while staying firmly within the law.
Strategic Wealth Protection with VIP Vaults
Securing your future with precious metals is a significant decision that requires more than just a transaction. At VIP Vaults, we act as a discreet guardian for your assets, providing the professional infrastructure needed to manage a high-stakes retirement portfolio. We specialise in offering a reliable sanctuary that operates independently of traditional banking systems. When evaluating if is gold a good investment for retirement Australia, the final piece of the puzzle is the reliability of your supply chain and the physical integrity of your storage solution. Our approach combines global security standards with the attentive, personalised service that high-net-worth retirees expect.
We provide a seamless pathway for those ready to transition from digital uncertainty to tangible security. Whether you're looking for a compact bullion locker or a larger private vault rental, our facilities are designed to offer absolute privacy and independence. By removing the middleman and the vulnerabilities of the banking grid, you gain total control over your wealth. Starting your journey involves a methodical process where we guide you through asset selection and secure logistics, ensuring your retirement fund is robust enough to withstand any financial volatility.
Investment-Grade Bullion Selection
Quality is paramount when building a portfolio meant to last decades. We stock LBMA-accredited gold bullion from internationally recognised refiners, including The Perth Mint, to ensure your holdings meet the highest global standards for purity and weight. Trustees often weigh the benefits of different formats to suit their specific liquidity needs. For a comprehensive analysis of these options, you can explore our guide on Gold Coins vs Gold Bars Australia: The 2026 Strategic Investor’s Guide. While minted bars offer a high level of finish and security features, cast bars provide a cost-effective way to accumulate larger volumes of metal for long-term wealth preservation.
Independent Private Vaulting
Our high-security facilities serve as a superior alternative to bank safety deposit boxes, which are increasingly scarce and often subject to institutional limitations. VIP Vaults offers a specialised environment where privacy and physical robustness are the primary objectives. We understand that for many retirees, the answer to whether is gold a good investment for retirement Australia is tied directly to the peace of mind that comes from knowing their wealth is physically present and professionally guarded. To begin securing your legacy, you can book a private consultation with our experts or organise a secure locker to house your investment-grade bullion today.
Securing Your Legacy with Tangible Wealth
Integrating precious metals into your long-term strategy provides a level of certainty that digital markets often fail to deliver. By choosing physical ownership over paper exposure, you eliminate counterparty risk and ensure your wealth remains accessible regardless of financial system volatility. We have explored how professional vaulting simplifies SMSF compliance and why LBMA-accredited products are the global standard for Australian portfolios. It's about moving from digital promises to physical certainty.
When you evaluate if is gold a good investment for retirement Australia, the answer lies in the stability it provides as a permanent store of value. Protecting your hard-earned superannuation requires a proactive approach that prioritises physical robustness and absolute privacy. At VIP Vaults, we provide the independent, non-bank high-security storage and transparent live pricing you need to build a resilient future. Our facilities offer the sanctuary your assets deserve, away from the traditional banking grid.
Secure your retirement wealth with VIP Vaults – Explore our bullion and vaulting solutions today.
Take the first step toward a more stable and independent retirement by securing your tangible assets today.
Frequently Asked Questions
Is it legal to hold physical gold in my Australian superannuation fund?
Yes, it's legal to hold physical gold within a Self-Managed Super Fund (SMSF). The bullion must meet a minimum purity of 99.5% to be considered investment-grade. Trustees must ensure the gold is stored according to strict ATO regulations and is fully insured. It's essential that the asset satisfies the "sole purpose test," meaning it is held exclusively to provide retirement benefits for fund members.
How much of my retirement portfolio should be allocated to gold?
Many financial professionals suggest a diversification of 5% to 10% in precious metals to hedge against market volatility. This allocation depends on your personal risk tolerance and retirement timeline. When considering if is gold a good investment for retirement Australia, a modest holding provides a stable foundation that doesn't rely on the performance of the ASX or traditional banking systems to maintain its value.
Can I store my SMSF gold in a home safe?
No, storing SMSF bullion in a home safe is effectively prohibited by the ATO. Regulations require that assets are kept separate from personal property to avoid any "personal use" benefit. Using an independent, high-security vault provides the third-party verification that auditors require. This professional arrangement ensures your fund remains compliant and protects you from the heavy tax penalties associated with non-complying storage solutions.
What happens to my gold if the vault provider goes out of business?
Your bullion is held under a bailment agreement, which means you retain legal title to the specific physical assets. Unlike a bank deposit where you're an unsecured creditor, gold in a private vault isn't on the provider's balance sheet. If the facility closes, your assets remain your property. They're typically transferred to another secure facility or returned to you directly under the terms of your storage contract.
Do I have to pay GST on gold bullion purchases in Australia?
No, investment-grade gold bullion is generally GST-free in Australia. To qualify as a "precious metal" for tax purposes, the gold must have a purity of at least 99.5%. This exemption makes physical bullion a cost-effective way to preserve wealth compared to other tangible assets that attract the tax. Always ensure you purchase LBMA-accredited products to guarantee they meet the specific purity standards required for the exemption.
How do I sell my gold bullion when I reach retirement age?
You can liquidate your bullion quickly by selling it back to a reputable dealer. Most dealers offer transparent live market pricing and will buy back investment-grade bars and coins instantly. This high liquidity is a primary reason why is gold a good investment for retirement Australia. It allows you to access cash to fund your lifestyle without the lengthy delays often associated with selling investment real estate or other large assets.
Is gold considered a "risky" investment for retirees?
Gold is generally viewed as a low-risk "insurance policy" rather than a speculative gamble. While the price fluctuates in the short term, its primary role is to preserve purchasing power over decades. It carries no counterparty risk, meaning its value doesn't depend on a bank's solvency. For many retirees, the greatest risk is having a portfolio entirely dependent on digital systems and paper assets that inflation can devalue.
What is the difference between a bullion locker and a bank safe deposit box?
A bullion locker in a private vault offers specialised security and independence that a traditional bank box cannot match. Private facilities provide comprehensive insurance specifically designed for precious metals and high-value assets. Unlike banks, which are increasingly withdrawing safe deposit services, private vaults offer discreet, personalised access. This independence ensures your wealth remains secure and accessible even if traditional financial institutions face a systemic crisis or operational restrictions.