What if the most reliable asset in your retirement portfolio is the one you can actually hold in your hand? Many Australian trustees are asking, "can my SMSF buy physical gold" as a strategy to distance their wealth from the inherent risks of the traditional banking system. It's a sophisticated choice for those seeking stability. You've likely felt the weight of increasing market volatility and want a tangible hedge that offers genuine independence. However, the concern regarding a potential ATO audit or a complex compliance breach often prevents investors from securing their future with precious metals.
This guide provides the definitive roadmap you need to integrate physical bullion into your fund with absolute certainty. You'll discover the specific legal requirements for 2026, including how to satisfy the Sole Purpose Test and the essential Arm's Length principle. We'll clarify the strict storage regulations that distinguish investment-grade bullion from collectables, ensuring your SMSF remains audit-proof. From high-security private vaulting solutions to the precise documentation required by your auditor, you'll gain the specialized knowledge to protect your wealth within a robust and compliant framework.
Key Takeaways
- Gain clarity on the legal framework under the SIS Act to answer "can my SMSF buy physical gold" while ensuring your Trust Deed is correctly updated to allow precious metal investments.
- Master the compliance requirements of the Sole Purpose Test and the Arm’s Length Rule to protect your fund from potential ATO breaches.
- Understand why residential storage is an audit minefield and how independent, high-security vaulting provides the necessary physical robustness for your assets.
- Implement a methodical step-by-step process for all bullion transactions to maintain a transparent, audit-ready paper trail.
- Discover the advantages of partnering with a discreet vaulting specialist to secure your fund’s future away from the traditional banking system.
Can Your SMSF Buy Physical Gold? Understanding the Legal Framework
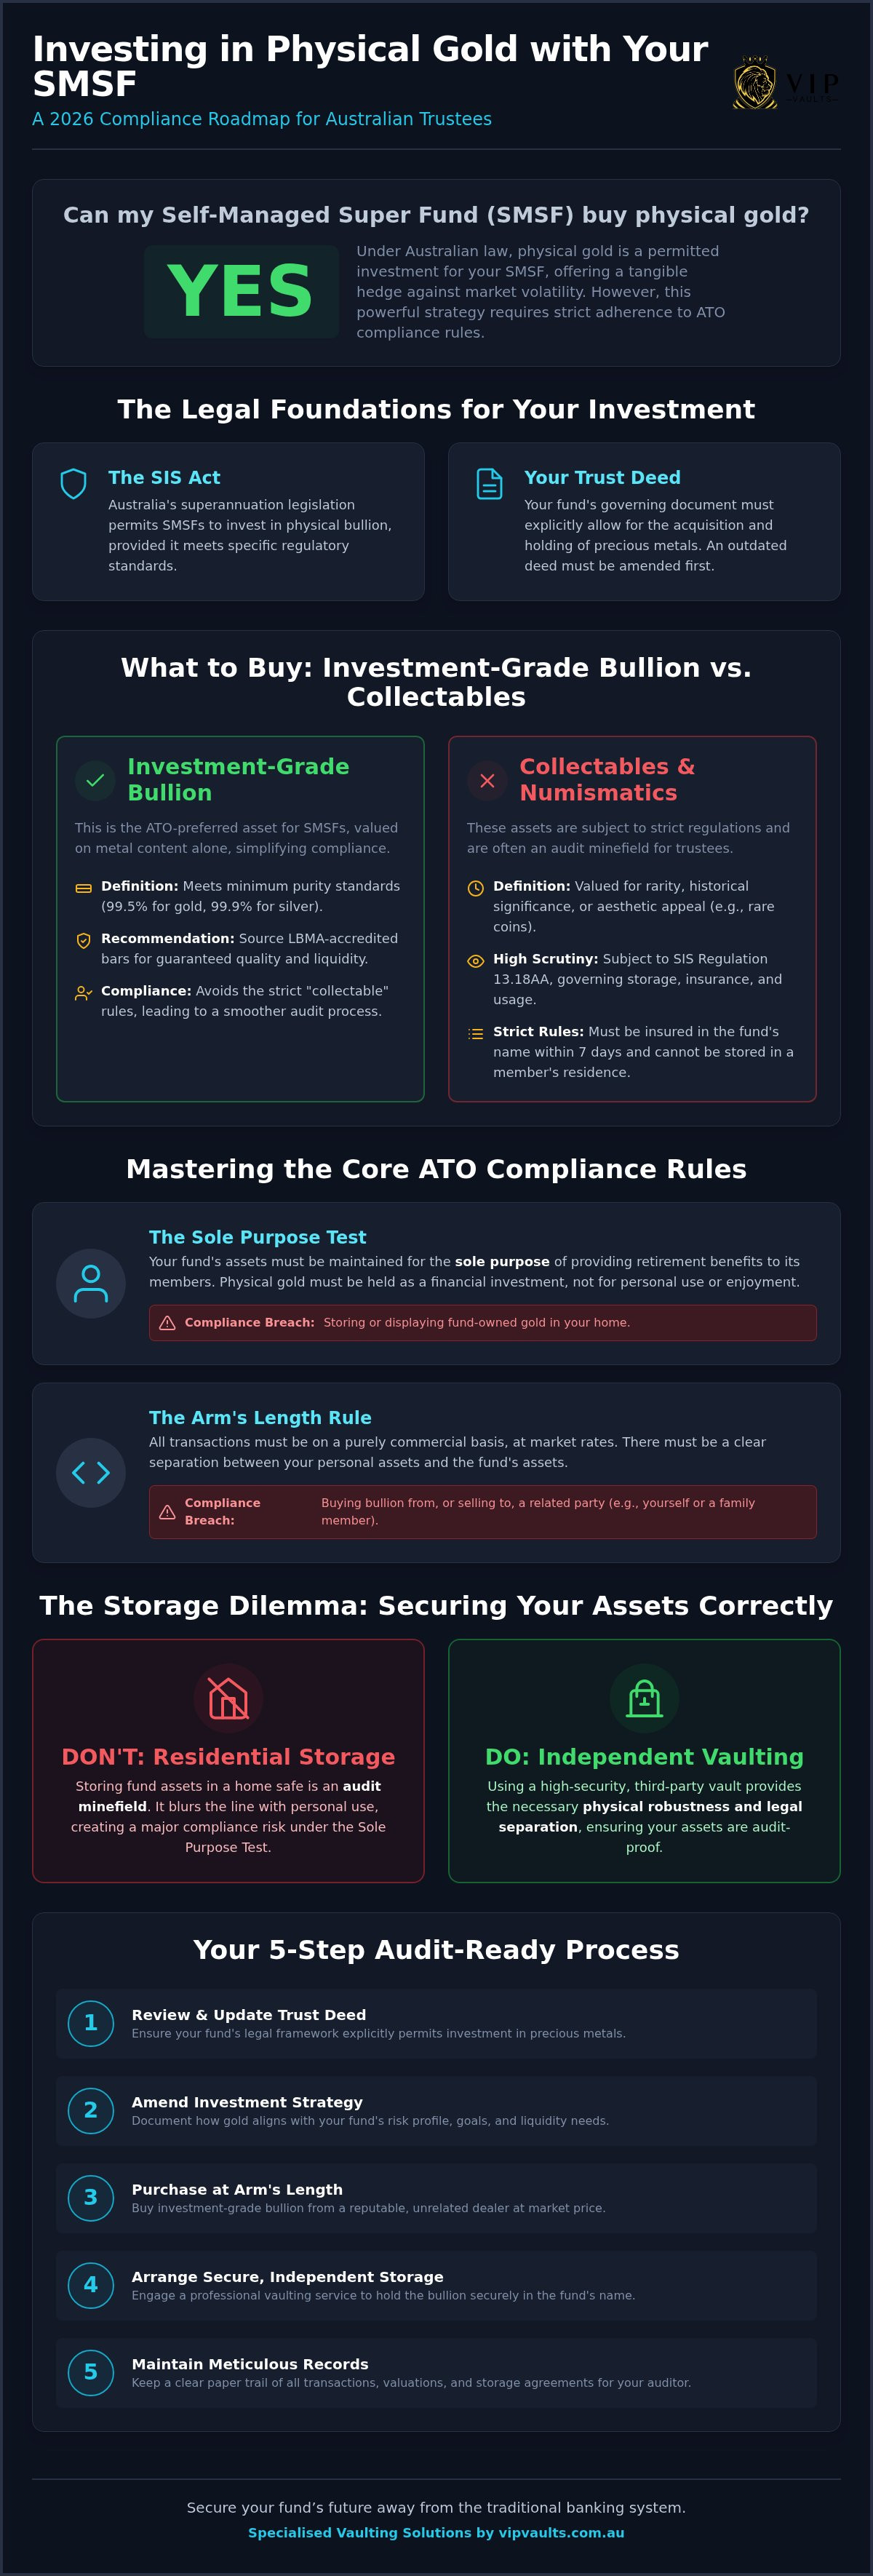
The fundamental question, "can my SMSF buy physical gold," is met with a definitive yes under current Australian law. Physical gold is a permitted investment according to the SIS Act, provided it meets specific regulatory standards. Within the broader context of Superannuation in Australia, Self-Managed Super Funds offer the unique flexibility to hold tangible wealth, a feature that has become increasingly attractive to trustees in 2026. However, legal permission at the federal level is only the first hurdle. Your fund's Trust Deed must explicitly allow for the acquisition and holding of precious metals. If your deed is outdated or silent on physical commodities, you'll need to formalise an amendment before making your first purchase.
It's vital to distinguish between investment-grade bullion and numismatic or "collectable" coins. The ATO applies different rules to each. Bullion is valued purely on its weight and purity. Collectables, such as rare or commemorative coins, are subject to strict SIS Regulation 13.18AA rules regarding storage, insurance, and display. In 2026, many trustees prefer bullion because it avoids the "collectable" tag. This choice simplifies the audit process while providing a robust hedge against traditional market volatility and currency devaluation.
The Definition of Investment Grade Bullion
To qualify as a financial investment rather than a collectable, your gold must meet a fineness of at least 99.5%. For silver, the standard is 99.9%. We recommend sourcing LBMA-accredited bars. The London Bullion Market Association (LBMA) sets the global benchmark for quality and integrity. Purchasing through a recognised bullion exchange ensures your assets are liquid and verifiable. This accreditation is your guarantee that the metal meets international standards, which is a critical detail your auditor will verify during the annual review.
Updating Your SMSF Investment Strategy
Before you buy, your written investment strategy must reflect the addition of precious metals. This document should outline how gold fits your fund's risk profile and long-term goals. Don't overlook liquidity. You must demonstrate that holding physical gold won't prevent the fund from meeting its expenses or making pension payments to members. A well-documented strategy isn't just a compliance task; it's your primary defence during an ATO audit. It proves that the decision to buy physical gold was methodical, deliberate, and aligned with the fund's sole purpose of providing for your retirement.
ATO Compliance and the Sole Purpose Test for Bullion
Every investment decision within your fund must satisfy the "Sole Purpose Test." This means your fund's assets are maintained for the single purpose of providing retirement benefits to its members. When you ask, "can my SMSF buy physical gold," you must also ask if the purchase is strictly for financial gain rather than personal enjoyment. Any hint of personal use, such as displaying fund-owned gold coins in your home, constitutes a major compliance breach. The ATO views such actions as a pre-retirement benefit, which can lead to your fund being declared non-complying and losing its concessional tax status.
The "Arm’s Length Rule" is another pillar of SMSF compliance. All transactions must be conducted on a purely commercial basis. You cannot purchase bullion from a related party, such as yourself or a family member, even if the price matches the market rate. Similarly, you cannot sell fund-owned gold to a related party. Maintaining a clear, documented separation between your personal wealth and the fund's assets is a legal necessity that protects the integrity of your retirement savings.
Avoiding the Collectables Trap
Distinguishing between bullion and collectables is vital for your storage strategy. Under SIS Regulation 13.18AA, "Collectables and Personal Use Assets" like rare coins or jewellery are subject to incredibly strict rules. These must be insured in the fund's name within seven days of purchase and cannot be stored in a member's private residence. Investment-grade bullion is generally exempt from these specific constraints because it's valued on metal content rather than rarity. However, to ensure your gold stays categorised as a financial investment, you must avoid assets with high numismatic premiums. According to the Moneysmart SMSF guide, trustees bear full responsibility for these decisions, making professional advice essential for maintaining compliance.
Valuation Requirements for Annual Audits
Your fund's assets must be valued at market rates as of 30 June each financial year. For physical gold, this requires using live spot price data to establish an accurate value for reporting. Your auditor will require specific evidence of existence and ownership to sign off on your annual return. This typically includes a storage agreement in the fund's name and a "Certificate of Existence" from your provider. Utilising a secure bullion locker ensures you receive the professional, audit-ready documentation required to satisfy these annual checks without the stress of manual verification. Providing buy and sell contracts alongside these certificates creates a transparent paper trail that demonstrates your fund is operating within the law.
Storage Requirements: Why Home Safes are an Audit Minefield
While the answer to "can my SMSF buy physical gold" is a clear yes, the choice of storage location often dictates whether your fund remains compliant or faces heavy penalties. Many trustees mistakenly believe a high-quality home safe provides sufficient security. From a regulatory perspective, it's rarely enough. Auditors view residential storage as a significant red flag because it complicates the "separation of assets" rule. You must prove that the fund's gold is kept entirely separate from your personal belongings. A safe located in a private residence makes this distinction difficult to verify, often leading to a qualified audit report.
Insurance presents another formidable hurdle. Most standard home and contents policies won't cover high-value bullion held within a superannuation structure. Even if you find a specialized provider, the premiums for residential storage are often prohibitive due to the increased risk of theft. By 2026, the landscape for traditional bank safety deposit boxes has also shifted. Many major institutions have phased out these services, leaving trustees to seek more specialized, secure alternatives that cater specifically to the needs of wealth protection.
The Case for Independent Private Vaulting
Independent vaulting offers total separation from the banking system and government institutions. This independence is a core requirement for trustees seeking a "silent partner" in asset protection. These facilities provide levels of security that residential safes simply cannot match. We utilise sophisticated biometric access, seismic sensors, and constant 24/7 monitoring to ensure the physical integrity of your investment. More importantly, professional storage provides a clear, third-party audit trail. Your auditor receives a formal storage agreement and a certificate of existence, satisfying the ATO's evidence requirements without the need for intrusive home inspections.
Insurance and Physical Robustness
Choosing professional storage simplifies the insurance process. High-security facilities often have pre-negotiated, comprehensive insurance arrangements, which means your fund's assets are protected by world-class underwriters from the moment they're vaulted. This level of physical robustness is essential for mitigating "sovereign risk" and ensuring your wealth remains accessible regardless of broader financial instability. When you choose private vaults Australia, you're investing in a sanctuary that prioritises both physical security and absolute privacy. This approach provides the peace of mind that your retirement savings are held in a facility designed specifically for high-stakes asset protection, far beyond the capabilities of a standard home safe.
The Step-by-Step Process for Purchasing Fund Bullion
Acquiring precious metals for your fund requires a methodical approach to ensure every transaction remains within the strict boundaries of Australian law. When trustees ask, "can my SMSF buy physical gold," they must first verify that their fund is legally structured to do so. This starts with the Trust Deed. You must ensure this foundational document explicitly permits the purchase of physical commodities. If it doesn't, you'll need to formalise an amendment before proceeding. Once the legal groundwork is set, you must open a dedicated SMSF bank account. Every cent used to purchase bullion must originate from this account, and every cent from a future sale must return to it. This creates a clean financial trail that proves no personal funds were commingled with retirement savings.
Sourcing your gold is the next critical phase. We recommend dealing only with reputable Australian exchanges that supply LBMA-accredited bullion. This accreditation guarantees the purity and weight of your bars, making them easier to value and sell in the future. When executing the purchase, the invoice must be issued in the name of the fund, not your personal name. This is a non-negotiable requirement for the Arm's Length Rule. If the paperwork doesn't match the fund's legal title, your auditor will likely flag the transaction as a compliance breach. While the legal answer to "can my SMSF buy physical gold" is straightforward, the execution must be precise to avoid administrative errors.
Managing the Paper Trail for Your Auditor
A successful annual audit depends on your ability to produce a comprehensive paper trail. You must retain all buy and sell contracts, settlement statements, and bank records that document the movement of funds. These documents prove that the transaction occurred at a fair market price and that the fund holds legal title to the asset. Additionally, you'll need a storage certificate or vault receipt from your provider. This document confirms the physical existence of the gold at the end of the financial year, providing the "proof of existence" that auditors demand.
Gold Coins vs. Gold Bars for SMSFs
Choosing between gold coins and cast bars often comes down to a balance of premiums and liquidity. Gold coins usually carry higher manufacturing premiums but can be easier to sell in smaller increments. Conversely, cast bars offer the lowest entry price per gram, making them an efficient choice for larger allocations. Both formats are easily managed within a bullion locker, where they remain secure and accessible. For many trustees, 1oz minted bars are often the preferred SMSF choice for divisibility. To begin building your fund's physical reserves, you can buy gold bullion through our secure exchange to ensure your assets meet the highest accreditation standards.
Securing Your Fund’s Future with VIP Vaults
Choosing the right partner is the final and most critical step for any trustee asking, "can my SMSF buy physical gold." VIP Vaults & Bullion Exchange Perth serves as a discreet guardian for your fund's wealth, providing a seamless bridge between acquisition and high-security storage. By purchasing your LBMA-accredited bullion and securing it within our independent facilities, you eliminate the logistical friction that often leads to compliance errors. This integrated approach ensures that every invoice, settlement statement, and storage receipt is perfectly aligned with your fund's legal name, simplifying your annual audit process and providing absolute clarity for your records.
Our status as a non-bank, independent vaulting centre provides a genuine safe haven for Australian wealth. In an era where many trustees harbour concerns about institutional transparency, we offer absolute privacy and physical robustness. We don't just store metal; we provide a sanctuary that's entirely separate from the traditional financial system. This independence is vital for meeting the arm’s length requirements discussed earlier, as it provides clear, third-party verification that your fund's assets are managed professionally. Our commitment to providing audit-ready documentation means you can invest with the confidence that your compliance obligations are fully met.
Tailored Storage Solutions for Bullion Portfolios
We provide a range of options designed to meet the specific scale of your retirement portfolio. From individual Bullion Lockers for smaller allocations to high-capacity private vaults for substantial holdings, our facilities are built to world-class security standards. Confidentiality remains our core operating principle. Access is strictly controlled through multi-layered protocols, including biometric verification, ensuring only authorised trustees can interact with the fund’s assets. This methodical approach to security reflects the gravity of the assets we protect and the long-term trust we build with our clients.
Start Your SMSF Bullion Journey Today
Securing your retirement with tangible assets starts with an informed strategy. Our specialists are available to discuss LBMA-accredited product options that suit your fund's specific liquidity and growth targets. Whether you're weighing the benefits of gold coins vs gold bars australia or you're ready to secure a private vault rental, we provide the expertise required for a compliant transition. Take the first step toward physical asset protection by contacting us to discuss your fund's requirements. We're committed to being the unshakeable partner your wealth deserves.
Secure Your Retirement with Physical Certainty
Integrating tangible assets into your superannuation is a strategic method for diversifying wealth away from traditional banking volatility. The answer to can my SMSF buy physical gold is a clear yes, provided you adhere to the strict compliance framework set by the ATO. Success depends on maintaining a clear separation of assets and ensuring your storage solution provides the physical robustness required for such a high-value investment. Avoiding the pitfalls of residential storage is essential for a clean audit and long-term peace of mind.
By choosing independent, high-security vaulting, you protect your fund from common regulatory hurdles while securing LBMA-accredited bullion that meets global standards. This professional approach provides the audit-ready documentation and discreet service necessary for a seamless investment journey. Secure your fund’s future with VIP Vaults & Bullion Exchange today and gain the stability that only physical asset protection can provide. Your retirement savings deserve the security of a trusted guardian and the permanence of precious metals.
Frequently Asked Questions
Can I store my SMSF gold at home in Australia?
Storing investment-grade bullion at a private residence is technically permitted, but it's a significant audit risk that we strongly advise against. You must prove the gold is kept entirely separate from personal assets, which is difficult to verify in a residential safe. If the gold is a collectable coin, residential storage is strictly prohibited under SIS Regulation 13.18AA. Professional vaulting is the most reliable way to satisfy an auditor and protect your fund's compliance status.
Does the ATO require an annual audit for physical gold held in an SMSF?
Yes, the ATO requires every Self-Managed Super Fund to undergo an annual audit by an independent, approved SMSF auditor. When you ask, "can my SMSF buy physical gold," you must prepare for this yearly verification. Your auditor will check the fund's financial statements and verify the physical existence of the metal. Providing a certificate of existence from a professional vaulting facility is the standard method for meeting these annual reporting requirements.
What happens if my SMSF buys gold from a family member?
Purchasing gold from a family member or any other related party is a direct breach of the Arm's Length Rule. All SMSF transactions must be conducted on a strictly commercial basis. You cannot buy assets from or sell assets to yourself, your relatives, or business associates. Engaging in such transactions can lead to severe penalties, including your fund being declared non-complying and losing its concessional tax status. Always source bullion from an independent dealer.
Is physical gold in an SMSF taxed differently than other investments?
Physical gold is generally taxed the same as other fund investments within the superannuation system. In the accumulation phase, income and capital gains are taxed at 15%. If the fund holds the gold for more than 12 months, it qualifies for a one-third discount, reducing the effective capital gains tax to 10%. If your fund is in the pension phase, any gains from selling the bullion may be tax-free, subject to relevant transfer balance caps and regulations.
Do I need to insure the gold held within my SMSF?
Insurance is mandatory for items classified as "collectables," such as certain gold coins, and must be in the fund's name. While it's not a strict legal requirement for investment-grade bullion, failing to insure such a high-value asset often breaches the trustee's duty of care. Most professional vaulting facilities include comprehensive insurance or offer it as a standard feature, ensuring your fund's wealth is protected against theft or physical damage without complex personal policies.
Can I use my SMSF to buy gold jewellery or ornaments?
You can buy gold jewellery, but these items are classified as "collectables and personal use assets" under SIS Regulation 13.18AA. This means they cannot be worn by members or stored in a private residence. They must be professionally stored, insured within seven days of purchase, and the storage decision must be formally documented. Because jewellery provides no immediate personal benefit, it often complicates the Sole Purpose Test compared to standard investment-grade bullion bars.
What documentation does my auditor need for the gold bullion?
Your auditor requires a complete paper trail to verify every transaction and the asset's existence. This includes original buy and sell contracts, settlement statements from the bullion exchange, and bank records showing the movement of funds from the SMSF account. Additionally, you must provide a storage agreement and a certificate of existence dated 30 June. These documents prove the fund holds legal title to the gold and that it's stored in a secure, independent facility.
Are there limits on how much gold my SMSF can hold?
There are no specific legislative limits on the quantity of gold an SMSF can hold. However, your investment strategy must justify the allocation. You must consider diversification, liquidity, and the fund's ability to pay member benefits. If your fund is heavily weighted in gold, your auditor will check if this aligns with the documented risk profile. It's essential that the acquisition is consistent with the fund's long-term retirement goals and stated investment objectives.